Financial technology
QuantMAx: quantitative signal research
A product experiment connects market variables, candidate signals, explanations and risk information while protecting proprietary strategy logic.
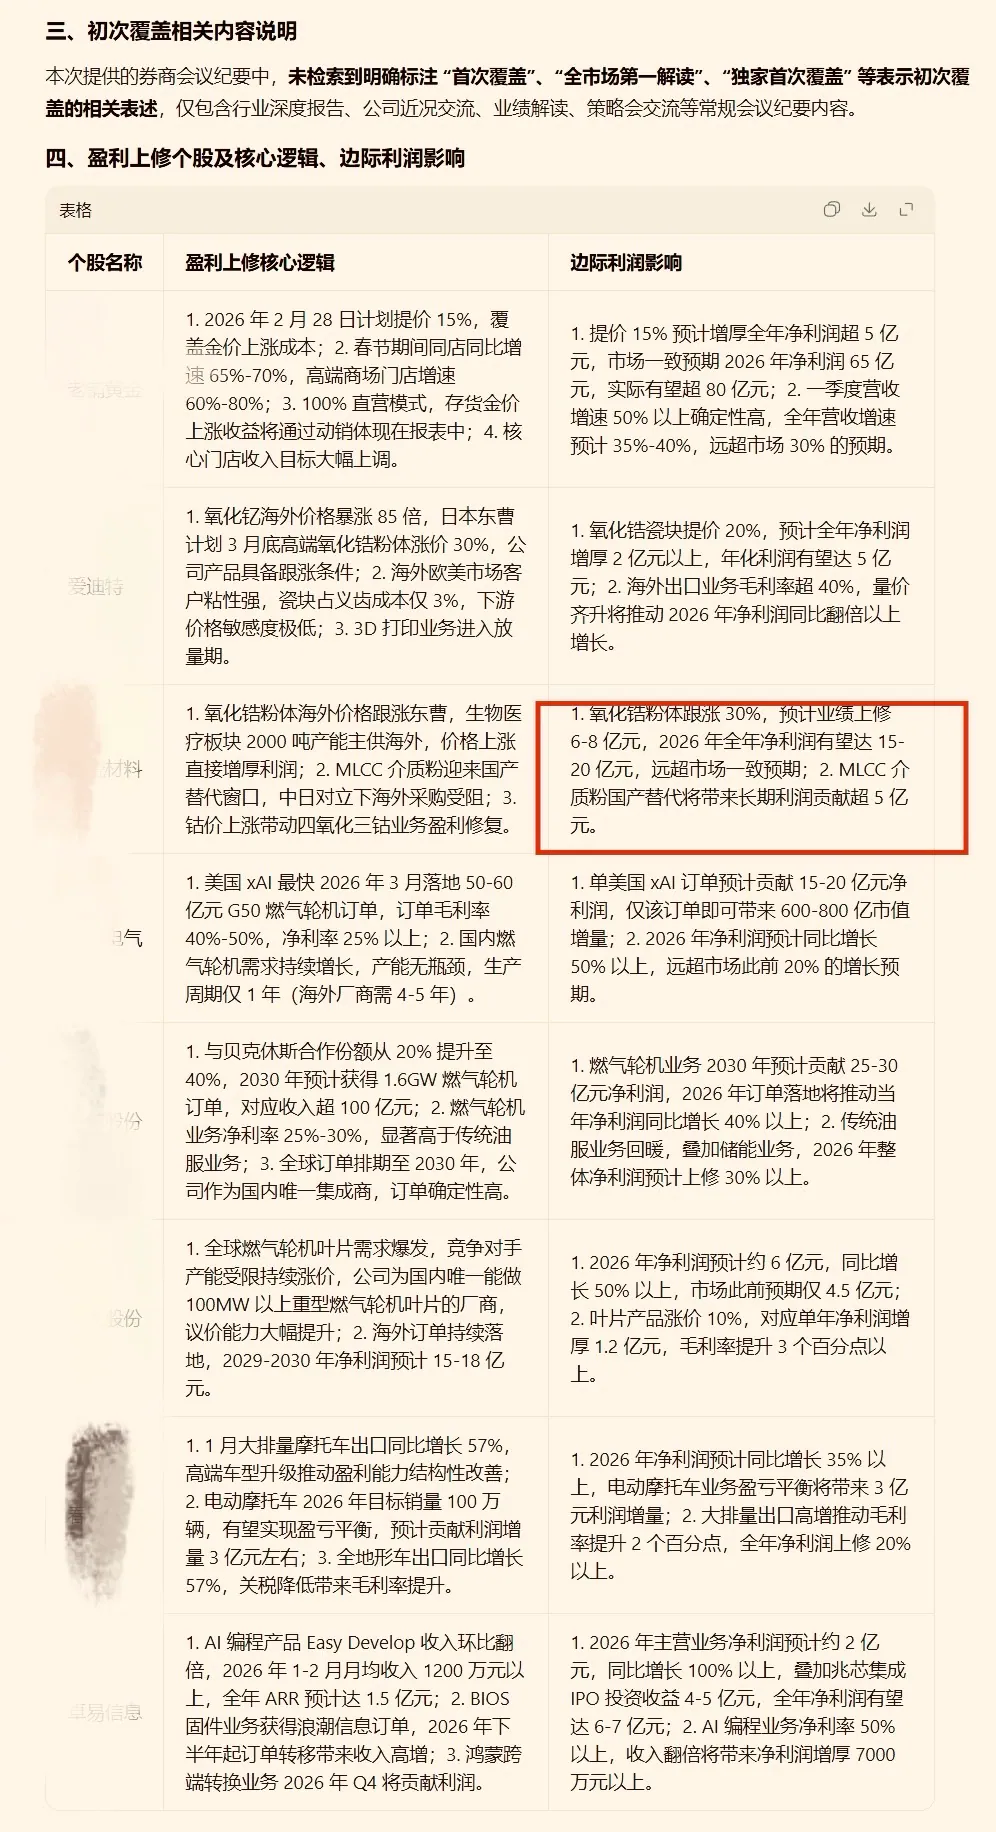
A product experiment connects market variables, candidate signals, explanations and risk information while protecting proprietary strategy logic.
Unexplained signals are difficult to assess, while publishing underlying strategy logic can expose proprietary assets.
The interface presents signal conditions and limitations alongside candidate outputs without disclosing the closed-source core.
Explainable candidates and risk information are organized while protecting the core strategy. Financial-product interactions rely on explicit evidence and clearly defined judgment boundaries.
AI methods
SIGNAL_ANALYSIS / EXPLAINABLE_SCREENING / RISK_DISCLOSURE
Workflows, pipelines and agents
Market data input / Private strategy / Explanation layer / Risk notice
Strategy parameters and licensed market data are excluded from public context. Outputs retain data timestamps, usage limitations and access audits.
The experiment makes signals and risk context inspectable. It is not investment advice or proof of returns.
This public project account describes documented work and its current stage. It does not imply independent verification, client endorsement or unreported commercial results.